

Imbalance as a fuse
More and more apartments, yet nowhere to live: why Central Asia faces an affordable rental crisis
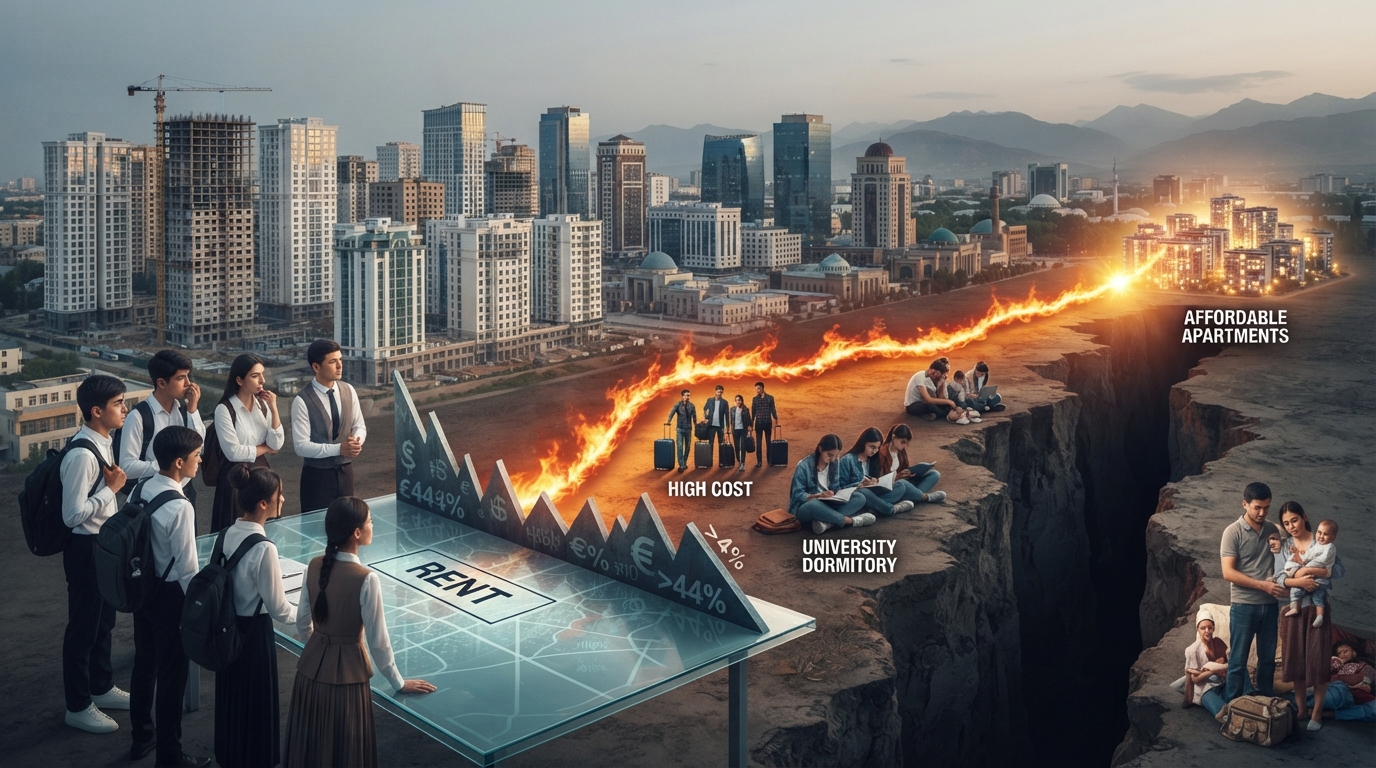
**Imbalance Like a Slow Match**
Central Asia is gradually approaching a situation where the main limitation of the urban economy will no longer be the sheer number of apartments built, but the affordability of long-term rentals for low- and middle-income people.
Kazakhstan, Uzbekistan, Kyrgyzstan, and Tajikistan are at different stages of urbanization, but the same problem can be traced in all four countries. Housing construction is growing, new residential complexes are appearing, urban boundaries are expanding, yet a significant portion of young people still faces difficulties finding independent housing. The reason is a structural mismatch between real estate supply and solvent rental demand.
Developers mainly focus on apartment buyers, whereas a growing segment of the urban population needs the opportunity to rent housing for several years rather than ownership. This gap is particularly noticeable in capitals, university centers, and major industrial cities. As a result, the construction of new square meters no longer automatically means an increase in housing affordability. A distinct segment of the housing problem emerges, which traditional real estate commissioning statistics hardly capture. Its consequences affect labor mobility, demographic behavior, educational opportunities, and the distribution of economic activity between regions.
The demographic prerequisites for a future shortage of affordable rentals have been shaping for decades. The population of Uzbekistan grew from approximately 20.6 million people in 1991 to over 39 million by the mid-2020s. In Tajikistan, over the same period, the population increased from roughly 5.4 to over 10 million, while in Kyrgyzstan it exceeded 7 million people. Kazakhstan demonstrates more moderate growth rates, but even here the population has surpassed 20 million.
The age structure is of great importance: in Uzbekistan, Kyrgyzstan, and Tajikistan, numerous young generations are gradually entering the period of independent employment and family creation. For the housing market, this means the emergence of millions of potential new households whose needs do not coincide with those of previous generations. Young professionals change jobs more often, enroll in universities in other cities, and postpone purchasing real estate until they achieve financial stability. At the same time, the emergence of a separate household increases the demand for housing units even without an increase in the total population. Therefore, demographic pressure on rentals can intensify much faster than the country's population grows as a whole.
Kazakhstan is the most vivid example of the divergence between construction activity and housing affordability. According to national statistics, in 2024, about 19 million square meters of housing were commissioned in the country, which became one of the highest figures in the post-Soviet period. However, a significant portion of the new supply is concentrated in Astana, Almaty, and other economically attractive centers, where the highest demand is simultaneously formed. In Astana, the population grew from approximately 600 thousand people in the mid-2000s to over 1.5 million by the mid-2020s. Almaty also continues to attract students, entrepreneurs, and specialists from other regions of Kazakhstan. Meanwhile, the high cost of buying an apartment turns ownership into a tool for capital accumulation, rather than just a way to meet housing needs. Investors purchase real estate for subsequent resale, short-term lease, or savings preservation. Such a model supports the construction sector, but does not guarantee the appearance of a sufficient number of apartments with moderate rent. Moreover, the growth of real estate's investment attractiveness can raise rental costs through the price appreciation of the purchased property itself. As a result, the expansion of supply is accompanied by the persistence of financial barriers for tenants.
In Uzbekistan, the problem takes on additional dimensions due to the high concentration of economic opportunities in Tashkent. The capital accumulates a significant portion of modern jobs, universities, medical institutions, and service sector enterprises. At the same time, internal migration flows from the Fergana Valley, Kashkadarya, Surkhandarya, and other regions are directed here. The construction of new residential areas and the implementation of the New Tashkent project expand the prospective supply of real estate, but their socio-economic effect depends on the price structure of future housing. New apartments are usually sold at market prices, which include the cost of land, utility infrastructure, loans, and the developer's profit. For young workers in retail, education, catering, and consumer services, such properties may remain unaffordable. Another feature of the Uzbek market is the noticeable role of family ownership and informal rental relationships. Some newcomers live with relatives or rent rooms without full contracts. This temporarily softens the housing deficit, but simultaneously conceals the real scale of unmet demand. Therefore, official indicators of housing availability do not allow an understanding of how many young citizens are able to independently rent a separate apartment.
Kyrgyzstan shows another variation of the same process, associated with a high territorial concentration of economic activity. Bishkek and adjacent areas of the Chuy Region attract a significant share of internal migrants, students, and young families. At the same time, the formation of the capital's agglomeration is accompanied by the expansion of suburban development, where housing affordability is often achieved at the cost of rising transport expenses. An apartment in a remote area may cost less, but daily commutes to work increase total household expenses. This is especially noticeable for workers with fixed schedules, students, and families with young children. Additional pressure is created by the limited supply of small apartments, high costs of building materials, and the dependence of development projects on buyers' financial capabilities. After 2022, the Bishkek market experienced an additional impact from migration flows related to the relocation of citizens from Russia and other countries. The surge in demand in certain segments showed how sensitive the local rental market is to relatively fast changes in the number of solvent tenants. For local households, this meant increased competition for a limited pool of apartments. Even the subsequent weakening of external demand does not eliminate the structural problem of the shortage of professionally managed long-term rentals.
In Tajikistan, the limited availability of affordable rentals is closely linked to the specifics of the national income model. A significant portion of family budgets is formed through remittances from labor migrants, primarily those working abroad. According to World Bank estimates, in certain years the ratio of remittances to the country's GDP exceeded 40%, ranking among the highest indicators in the world. These funds support consumption, the construction of private houses, and apartment purchases, but do not necessarily contribute to the development of an organized rental sector. Households often perceive real estate as a long-term family asset intended for several generations. Dushanbe simultaneously concentrates administrative institutions, higher education, trade, and modern services. Young people from rural areas face the need to live in the capital with relatively limited personal incomes. Since the formal market for long-term rentals is insufficiently developed, personal connections, shared living, and informal agreements play an important role. Such mechanisms reduce current expenses, but limit the independence of young workers and students. Thus, a high volume of private housing construction can coexist with an insufficient affordability of independent living.
The economic essence of the problem lies in the difference between the apartment sales market and the rental services market. A developer receives the main revenue after selling the property, and is therefore interested in the maximum sale price and a quick return on invested capital. An institutional landlord, on the contrary, evaluates real estate through future cash flows, operating expenses, and the tenancy duration of renters.
In Central Asia, the first model is much more widespread than the second, as professional operators of mass rental housing have not yet formed a sector of comparable scale. An additional obstacle is the cost of long-term financing, especially with high interest rates and limited access to cheap investment resources. If an apartment worth $60 thousand brings the owner $400 a month, its gross annual rental yield is 8%. After accounting for repairs, taxes, vacancy periods, and management, the actual yield turns out to be lower. With a high alternative yield on financial instruments, building housing specifically for rent becomes less attractive. As a result, supply is mainly formed by individual owners, each of whom independently determines the price and living conditions. This exacerbates market fragmentation and prevents the emergence of stable pricing standards.
The ratio of rent to household disposable income is of particular importance. In international housing analytics, housing costs exceeding 30% of income are often considered a sign of increased financial burden, although this indicator is not a universal threshold. For a young family with a total monthly income of $800, a rent of $350 means that nearly 44% of earnings goes toward the apartment alone. After utility bills, transport, and daily expenses, the ability to accumulate a down payment for a mortgage drops sharply. A peculiar housing trap arises: high rent prevents the transition to ownership, while the inability to buy an apartment maintains dependence on the rental market.
Students face even tougher constraints, as their incomes are often irregular or entirely dependent on family support. In cities with a large number of universities, demand is additionally concentrated before the start of the academic year. Given a shortage of dormitories, this leads to a seasonal increase in the cost of rooms and small apartments. Consequently, rental affordability is determined not only by the average monthly price, but also by payment stability, deposit size, and contract terms.
International experience shows that mass housing construction in itself does not guarantee the emergence of an affordable rental sector. Vienna is an example of a city where municipal and subsidized housing historically play an important role in curbing housing expenses. About a quarter of the city's population lives in municipal housing, and taking into account the subsidized sector, the coverage is significantly broader. In Germany, long-term renting has become a sustainable form of living thanks to developed legislation, professional property management, and the institutional structure of the market. However, transferring such models to Central Asia is complicated by differences in fiscal capacities, financial markets, and the land relations system. In post-Soviet states, the mass privatization of the 1990s formed a high share of private housing ownership. At the same time, the state rental fund significantly shrank, and a full-fledged commercial sector of professional renting did not fill the vacated space. Historically, the region's housing policy was oriented primarily toward increasing the number of property owners. Therefore, mechanisms to support real estate purchases developed noticeably more strongly than tools to ensure affordable long-term tenure. Today, the consequences of this institutional choice are particularly noticeable against the backdrop of demographic growth and internal migration.
A shortage of affordable rentals can gradually alter the economic geography of Central Asia. When the cost of living in the largest cities grows faster than the incomes of young specialists, the territorial mobility of the labor force begins to be constrained by housing expenses. Enterprises may face staff shortages even if potential workers are available in other regions. Universities risk losing applicants for whom living expenses are comparable to tuition costs. Young families postpone independent life and childbirth, as buying real estate requires significant savings, and renting does not provide sufficient financial predictability.
At the same time, social stratification is intensifying between urban real estate owners and generations entering the housing market without family assets. For Kazakhstan, this contradiction manifests against the backdrop of a relatively developed construction sector; for Uzbekistan, it is tied to demographic pressure; for Kyrgyzstan, it is determined by the concentration of opportunities in the capital; and for Tajikistan, it is aggravated by the specifics of income and the migration economy. The common thread becomes the transformation of access to rental housing into an independent factor in the distribution of human capital.
Central Asia may face not a physical absence of apartments, but a lack of housing that is affordable, located near workplaces, and offered on predictable terms. It is precisely this gap between the quantity of real estate built and the opportunity to live independently that forms the growing structural contradiction of the region's urban development.