What tax incentives and government support measures have been adopted for the electrical engineering industry
Resolution of the President No. PP-325 dated September 12, 2026, establishes tax and financial incentives to attract major investors and support local manufacturers of electrical products.
What tax incentives and state support measures have been adopted for the electrical engineering industry
Presidential Decree No. PP-325 dated September 12, 2026, introduces tax and financial incentives aimed at attracting major investors and supporting local manufacturers of electrical products.
**Tax incentives and preferences**
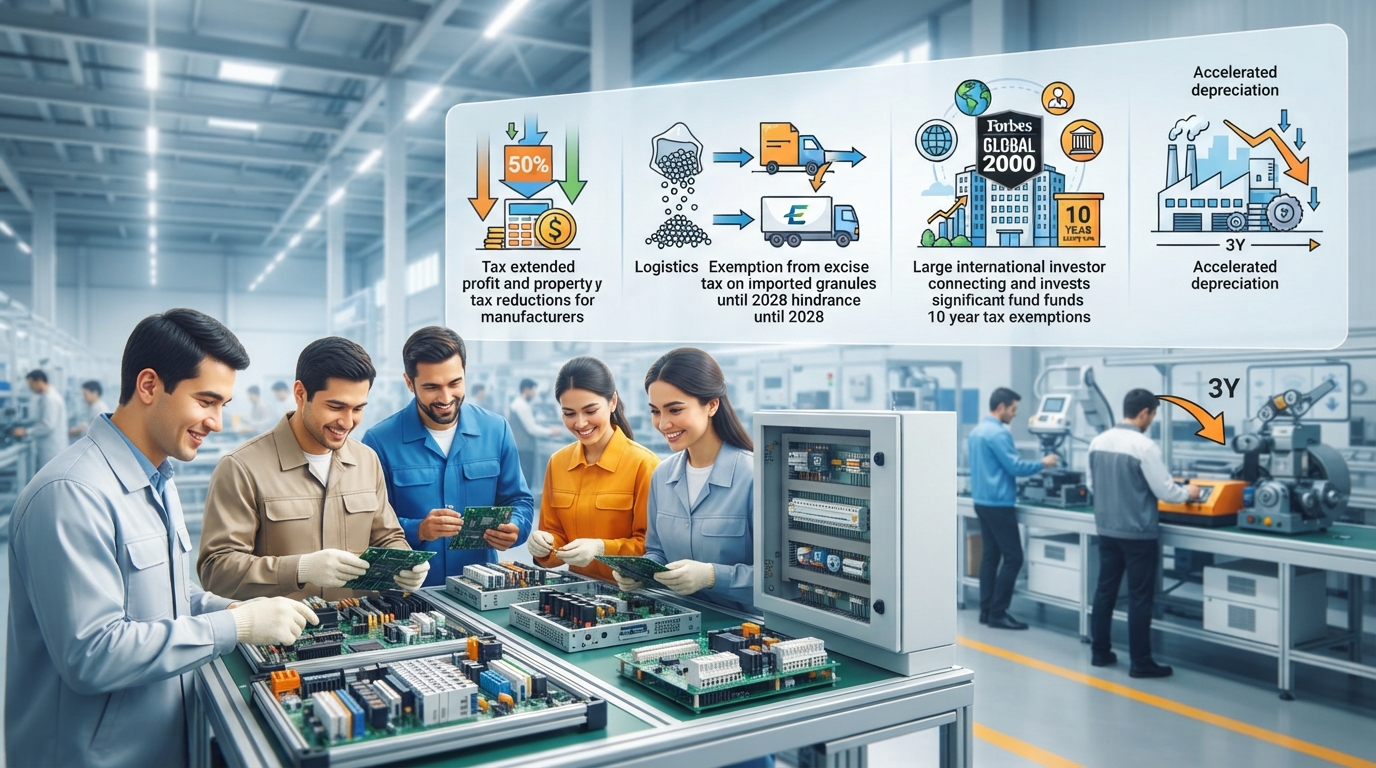
Until January 1, 2028, manufacturers of electrical products are exempt from paying excise tax on the import of polyethylene granules for their own needs.
The validity period of previously established tax incentives — a 50% reduction in corporate income tax and property tax rates for electrical industry enterprises whose share of revenue from the sale of electrical products at the end of the reporting period is at least 80% of total revenue — is extended until January 1, 2030.
Domestic manufacturers supplying raw materials, materials, and components to electrical industry enterprises registered on the Single Electronic Platform of the Agency for Industrial Cooperation and Public Procurement (cooperation.uz) are granted an incentive in the form of a 50% reduction in the property tax rate from January 1, 2027, to January 1, 2030. The condition is that at the end of the reporting (tax) period, revenue from the sale of these products must account for at least 50% of total revenue.
This incentive does not apply to state-owned enterprises and legal entities with a state share in the authorized capital of 50% or more.
Major international investors ("Forbes Global 2000") with an investment volume of USD 50 million or more are exempt from land tax, property tax, and corporate income tax for 10 years. At the same time, the investment agreement must include obligations to increase value added to over 40% within 3 years, as well as to allocate at least 3% of annual profit to research and development (R&D).
Business entities under new investment projects in electrical engineering are granted the right to accelerated depreciation of production buildings and technological equipment within 3 years from the date of their commissioning.