Uzbekistan will get more entertainment: cinema, theaters, and children's content have been exempted from five taxes for 10 years
In Uzbekistan, large-scale tax exemptions for nearly ten years have been introduced for a number of organizations in the field of culture and art. Exemption from paying five taxes applies, among others, to cinematography enterprises, non-state theaters, and creators of content for children. The exemptions also extend to employees of these organizations. According to the information service of the Tax Committee, the grace period is in effect from September 1 […]
Uzbekistan to get more entertainment: cinema, theaters, and children's content exempted from five taxes for 10 years
In Uzbekistan, large-scale tax incentives have been introduced for almost ten years for a number of organizations in the field of culture and art. Film industry enterprises, non-governmental theaters, and creators of content for children, among others, are exempt from paying five taxes. The benefits also apply to employees of these organizations.
According to the information service of the Tax Committee, the grace period is in effect from September 1, 2026, to January 1, 2036. These measures are provided for by the presidential decree of June 2, 2026, "On large-scale measures for the further development of the spheres of culture, art, and literature."
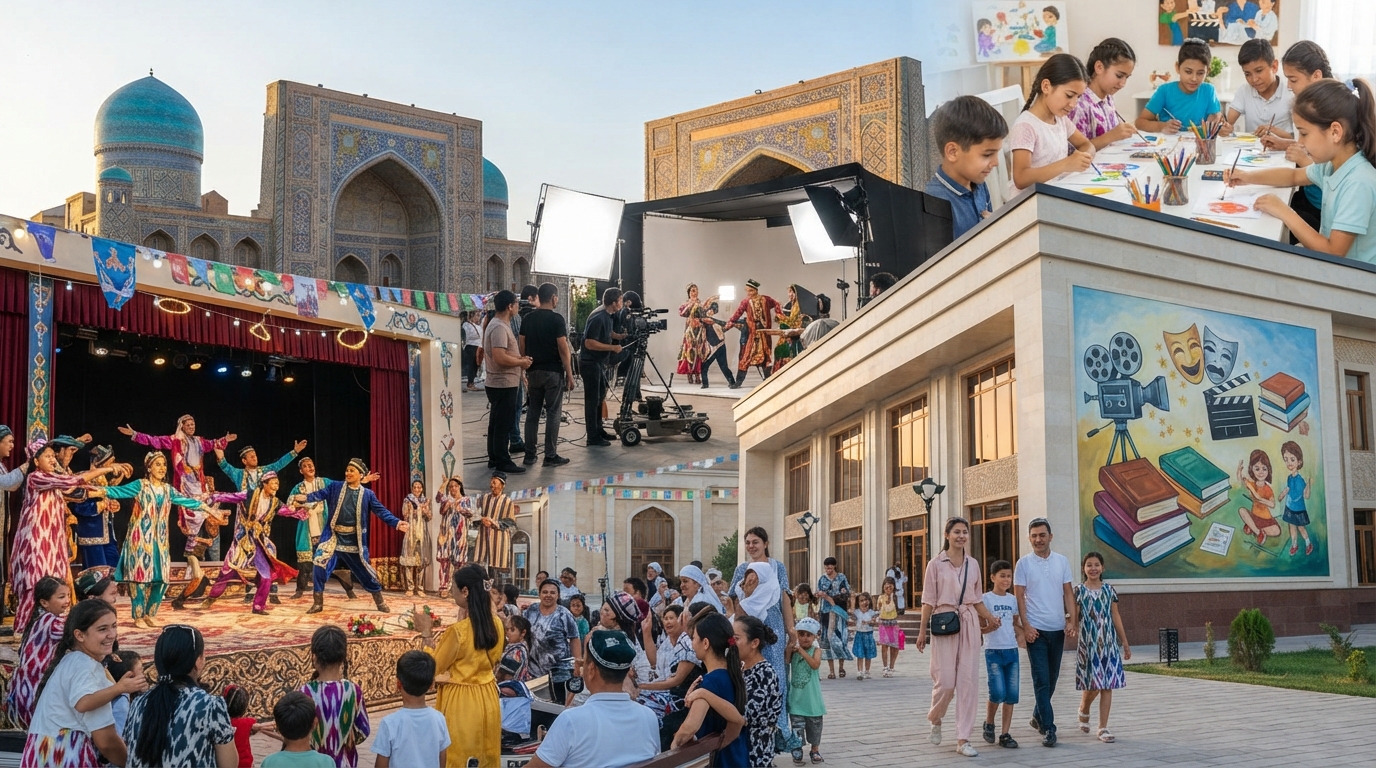
Tax relief applies to organizations whose main activity is concert and performance activities and cinematography, as well as to creators of content for children. The list of recipients includes non-governmental theaters and theater studios, as well as private educational organizations operating in the field of culture and art.
These organizations are exempt from paying value-added tax (VAT), corporate income tax, turnover tax, land tax, and property tax. Their employees, in turn, are exempt from personal income tax (PIT).
A separate measure is provided for foreign companies participating in the creation of film products on the territory of Uzbekistan. Income received from such activities is not included in the tax base when taxing non-residents' income at the source of payment.
Thus, the state expects to create more favorable conditions for the development of national film production, non-governmental theaters, children's content, and private education in the field of art.