

Uzbek lawyer in Chicago: what will the US experience in consumer credit and debt disputes give to Uzbekistan?
Currently practicing in consumer finance and creditors' rights litigation at Mandarich Law Group in Chicago
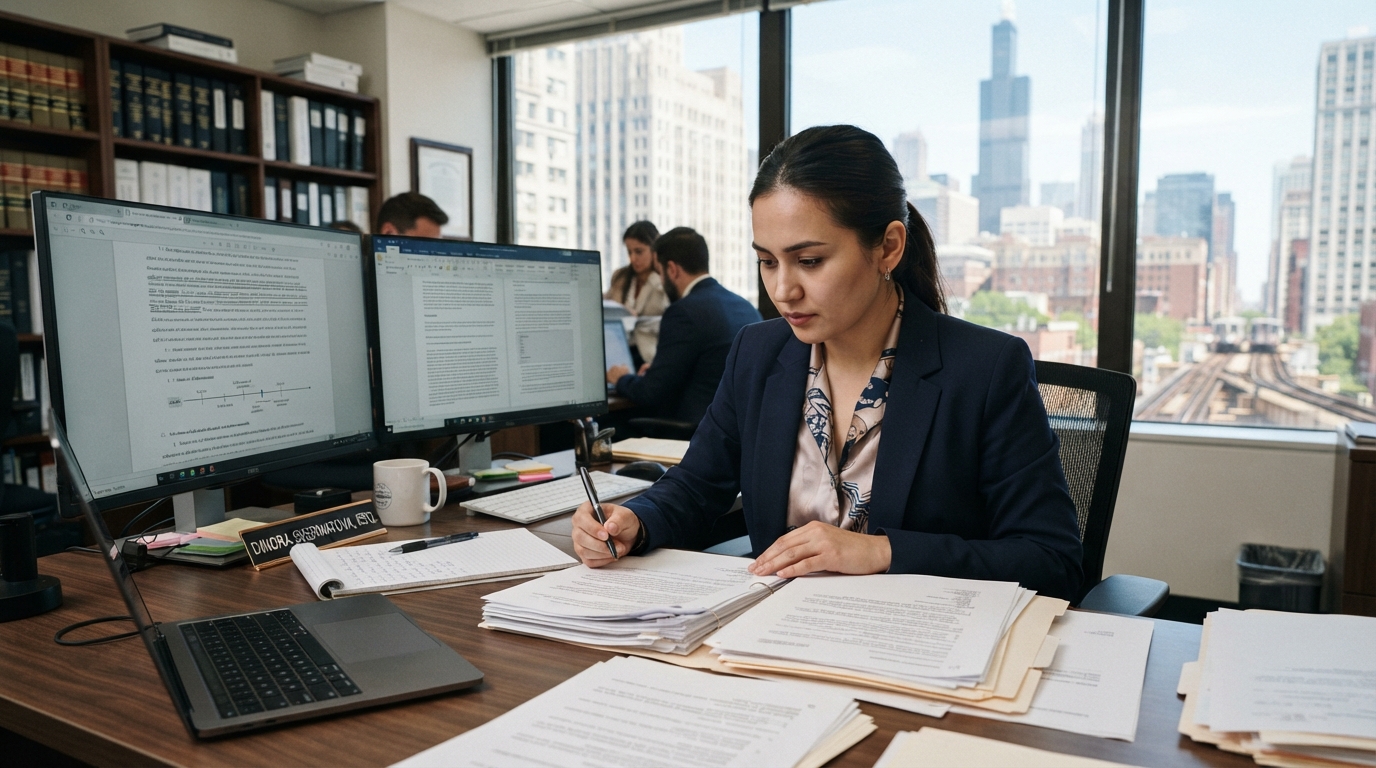
Uzbek lawyer in Chicago: What does the US experience in consumer credit and debt disputes offer Uzbekistan?
Dinora Shermatova, a lawyer from Khorezm, graduated from Tashkent State University of Law. As a recipient of the "El-Yurt Umidi" Presidential Scholarship, she completed her master's degree (LL.M.) at the University of Illinois College of Law in the USA. Currently, she works at the Mandarich Law Group firm in Chicago on litigation involving consumer finance and creditors' rights. Her scientific articles in this field have been published in international journals.
In Chicago, you deal with court cases on consumer finance and creditors' rights every day.
– In the US, a debt dispute usually begins with a creditor or a debt-buying company filing a lawsuit in a state court. After that, the documents are officially served on the debtor. If the debtor does not respond within the specified timeframe, the creditor requests a default judgment. A large part of my work falls into this exact stage. I prepare default judgment packages for superior courts in various counties of California, and I analyze and redraft documents rejected by the court. Once the decision is issued, the enforcement stage begins: wage garnishment, bank account levies, and so on. Strict procedural rules apply at every stage. An error in a single date or amount can lead to the court rejecting the document. Therefore, accuracy is the most important criterion in this work. Currently, training new employees to enter court judgments into the system is also one of my duties.
– The biggest difference lies in the specialization of the system. In the US, disputes over consumer debt have become a separate area of practice. For this, there are special laws, regulatory bodies, judicial practice, and lawyers specializing in this field. In Uzbekistan, however, such disputes are considered within general civil cases. The second difference is in the debtor protection mechanisms. In the US, when a creditor applies to the court, they must prove with documentation the origin of the debt and how the debt was transferred from one party to another. This requirement is strictly enforced, especially if the debt has been sold.
– Unpaid consumer loans are often not collected by the bank that issued them. The debt is sold, then resold again, resulting in an entire "chain of claims." In my article, I analyzed whether a link in this chain can be unilaterally revoked, using the example of US law as well as East European and European Union civil law. My conclusion is that in both systems, once the transfer of debt takes place, it cannot be unilaterally revoked. The main difference lies elsewhere: in how transparent the chain is for the debtor and the court. In the US, debt sellers often do not assume responsibility for the accuracy of information. Debt recovery agreements remain strictly between commercial parties, leaving both the consumer and the court unaware of them. The European Union, however, through Directive 2021/2167, imposed an obligation on debt sellers to provide information, while granting consumers the right to be informed of the debt transfer and to raise against the new owner all objections they had against the original creditor. I believe this is an important lesson for Uzbekistan as well. As the debt market develops, the debtor needs to know exactly whose hands their debt is in.
– In the US, the main document is the federal Fair Debt Collection Practices Act (FDCPA) and Regulation F based on it. They strictly define when and how a debt collector can contact a debtor, and what information they are obligated to provide. Threatening, deceiving, or putting pressure on the debtor's workplace or relatives is prohibited. The debtor has the right to dispute the validity of the debt, and in such cases, the collector must stop collection until the debt is proven. For a violation, the debtor can go to court and collect compensation. Reforms in this direction have also begun in Uzbekistan, but a specialized, detailed, and practice-tested procedure is still in the formation stage. Therefore, I think studying the US experience is beneficial.
Default judgments make up a large portion of debt collection in the US.
– Many debtors do not respond to the court at all, which is why default judgments are widespread. However, this does not mean it is an "automatic" decision. The court requires the creditor to provide documents confirming the debt amount, notarized statements, proof that the documents were properly served to the debtor, and the chain of ownership if the debt was sold. In California, these requirements are particularly strict. That is why I work every day with documents rejected by the court. The main lesson for Uzbekistan is that fast and efficient collection and the protection of debtor rights are not mutually exclusive. Clear evidence standards ensure both.
Lending and debt collection are moving to apps and messengers.
– This is one of the most pressing issues today. In digital lending, companies possess the debtor's personal data, phone contacts, and location. If this information is used without control during the collection process—for example, sending messages to the debtor's acquaintances or exerting pressure on social networks—this constitutes a serious violation of personal privacy. Currently, I am working on an article regarding the alignment of US debt collection legislation with modern data protection requirements.
– Regulation F permits electronic communication, but under strict conditions. The debtor must be given the option to stop communication. Messages on social networks must not be sent publicly or in a way visible to others. The number and timing of calls are also restricted. In Uzbekistan, buy-now-pay-later services and online microloans are developing rapidly. Setting clear rules before the market expands is much easier than resolving problems that arise later.
You have submitted proposals to the Central Bank and the Supreme Court of the Republic of Uzbekistan.
– My proposal is aimed at developing specialized practice in consumer finance disputes and creditors' rights in Uzbekistan based on the US experience. It covers standards for protecting debtors during debt collection, clear evidence requirements for proving creditors' claims in courts, and issues of ensuring transparency when transferring debt to third parties. I am pleased to say that the Supreme Court and the Central Bank of the Republic of Uzbekistan reviewed my proposal and plan to use it in future reforms and development efforts. For me, this is a great responsibility and an opportunity to apply the knowledge I gained in the US for the benefit of my Homeland.
– Everyone. Debtors will know their rights clearly and be protected from unfounded or illegal collection. For banks and financial institutions, clear, predictable rules reduce risk and increase market trust. For courts, standardized evidence requirements allow cases to be heard faster and with better quality. Ultimately, this also positively impacts the investment climate and the stability of the financial system.
– My academic work stems directly from my practical experience. First, my article comparing the unilateral revocation of claims chains in consumer credit under US and Eastern European civil law was published. Second, my article on the application of the secured transactions doctrine established in Article 9 of the US Uniform Commercial Code to cross-border consumer finance contracts was also published. Third, I am working on a comparative procedural analysis of the enforcement of creditors' rights in US state courts. This study aims to compare US and Uzbek judicial practice.
– I want to continue specializing in civil and commercial litigation, specifically in consumer finance and creditors' rights practice in the US. As a practicing lawyer, my goal is to obtain an attorney license in both the US and Uzbekistan. At the same time, I will continue my research activities. My goal is to serve as a bridge between the two countries: introducing advanced US experience in consumer finance and creditors' rights into Uzbekistan, and promoting the legal system of Uzbekistan in the international academic community.
– Choose a specific field rather than general "foreign law" and go deep into it. Consumer finance, fintech, and debt collection law are fields with a great future. Pay special attention to civil procedure, because in practice it is procedural knowledge that plays a decisive role. Do not be afraid to write scientific articles: research based on your practical experience is highly valued in the international community. Most importantly, do not be afraid to learn, deeply analyze how the knowledge you acquire can contribute to the development of the field, and aim for it to bring benefit to everyone!