

The small fee raising big questions for India's payments revolution
Since its launch in 2016, UPI has become a central part of India's digital payments economy.
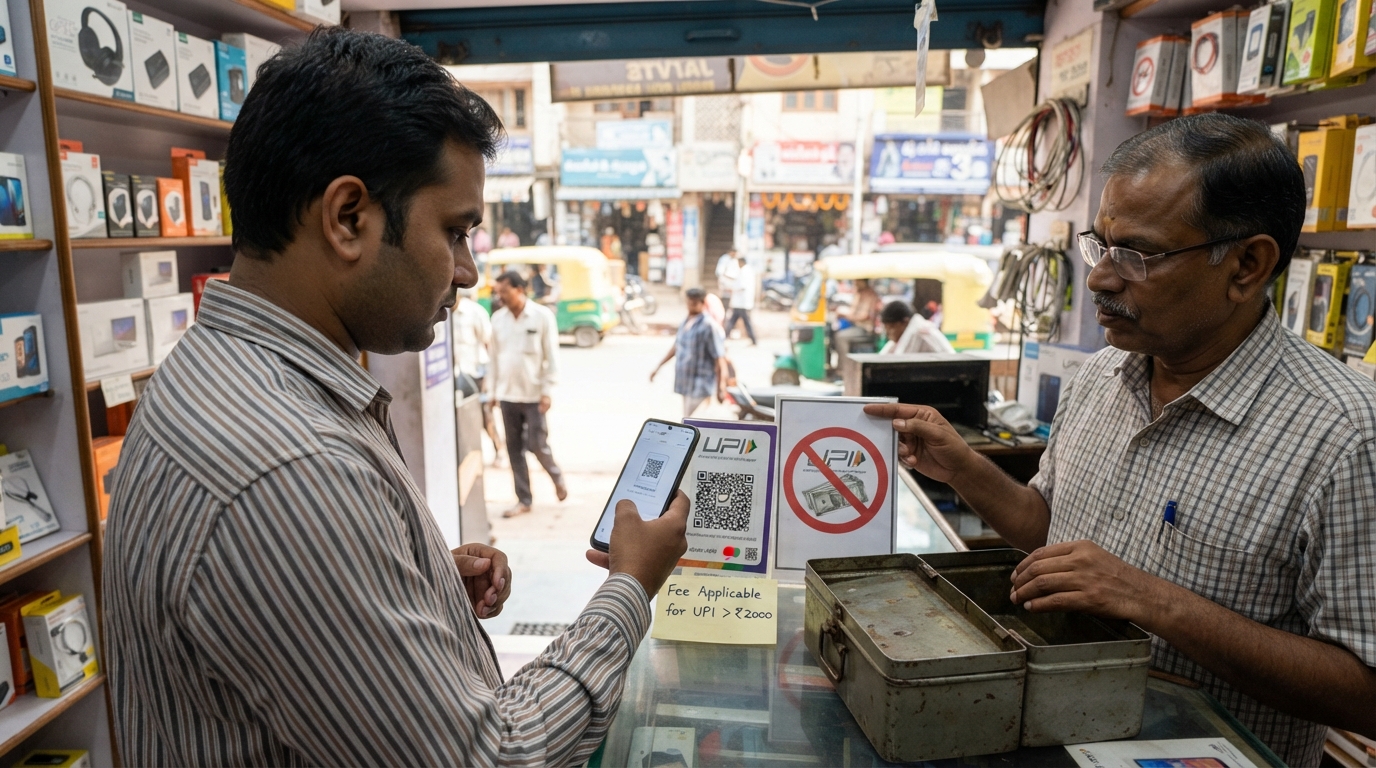
The small fee raising big questions for India's payments revolution
UPI is often called the backbone of India's digital payments system
India’s move to impose a fee on some transactions made through its hugely popular digital payments platform has triggered discussion about what it could mean for businesses.
On Tuesday, the National Payments Corporation of India said a 0.4% fee will take effect from 15 October on certain UPI (Unified Payments Interface) payments above 2,000 rupees (£15; $21) made by customers to businesses.
The fee must be paid by businesses, and they will not be permitted to pass the cost on to consumers, the NPCI said.
The government says the new levy will help ensure UPI remains sustainable over the long term, but experts fear it could increase costs for businesses and make them less willing to use the system.
Introduced in 2016, UPI lets people send and receive money instantly through mobile apps. Its simplicity has made it a key part of daily life in India, used by everyone - from small vendors to booming businesses.
So far, the government, banks and payment firms have largely covered the cost of operating and expanding the UPI network.
The new fee - called the Merchant Discount Rate (MDR) - is intended to help meet some of those expenses.
The government has said MDR is not a tax or a fee collected by the government or NPCI, which runs the UPI system.
UPI payments system is used across merchants in India from small vegetable vendors to gas stations
The charge will not apply to every UPI payment.
Person-to-person transfers will stay free, no matter the amount. Merchant payments of up to 2,000 rupees will also remain free. QR-code merchant payments in rural and semi-urban areas will not be subject to MDR either.
The government said "approximately 96% of person-to-merchant transactions will remain unaffected", either because they fall below the threshold or because they are covered by the zero-MDR framework for small merchants.
Some merchant payments above 2,000 rupees, including those for railways, telecom services, insurance, fuel and agricultural inputs, will instead face a flat fee of five rupees.
For other transactions above 2,000 rupees that are subject to MDR, the charge will be 0.4% and limited to 300 rupees per transaction. That cap applies to transactions of 75,000 rupees or more.
The regulator has said the funds will be used to support investment in areas such as payment infrastructure, resilience, innovation and cyber security.
The decision has prompted debate in India.
Some social media users say charging merchants could undermine one of UPI’s biggest advantages - that it has been free to use. Others have warned that some merchants may switch to cash for larger transactions rather than absorb a fee they did not previously have to pay.
Krishnamurthy Subramanian, a former chief economic adviser to the Indian government, said the economics of a system such as UPI cannot be "evaluated using private cost versus private benefit".
Speaking to news channel CNN-News18, Indian entrepreneur Ashneer Grover said there can be a situation where "a shopkeeper could simply refuse to accept a UPI payment of 2,000 rupees and ask you to pay entirely in cash. Then you will go back to using cash".
Others say a fee is necessary to help finance and expand the payments system.
"When government funds the subsidies paid for UPI, that amount comes from tax payers' pocket. Moving to market-linked pricing mechanism removes this tax burden and directly links the cost to large businesses which benefit from UPI," said Bipin Preet Singh, CEO of fintech firm MobiKwik.
Since its launch a decade ago, UPI has become a central pillar of India's digital payments economy. In August, UPI processed a record 24.51 billion transactions worth 29.82 trillion rupees (roughly $311bn), according to NPCI data.
The question now is whether the new charges will alter how businesses use UPI, especially for larger payments.