

Highly liquid assets of Uzbekistan's banks grew by 51.3%
As of October 1, 2026, highly liquid assets of Uzbekistan's banks reached 227.3 trillion soums, and the liquidity coverage ratio stood at 269.6%.
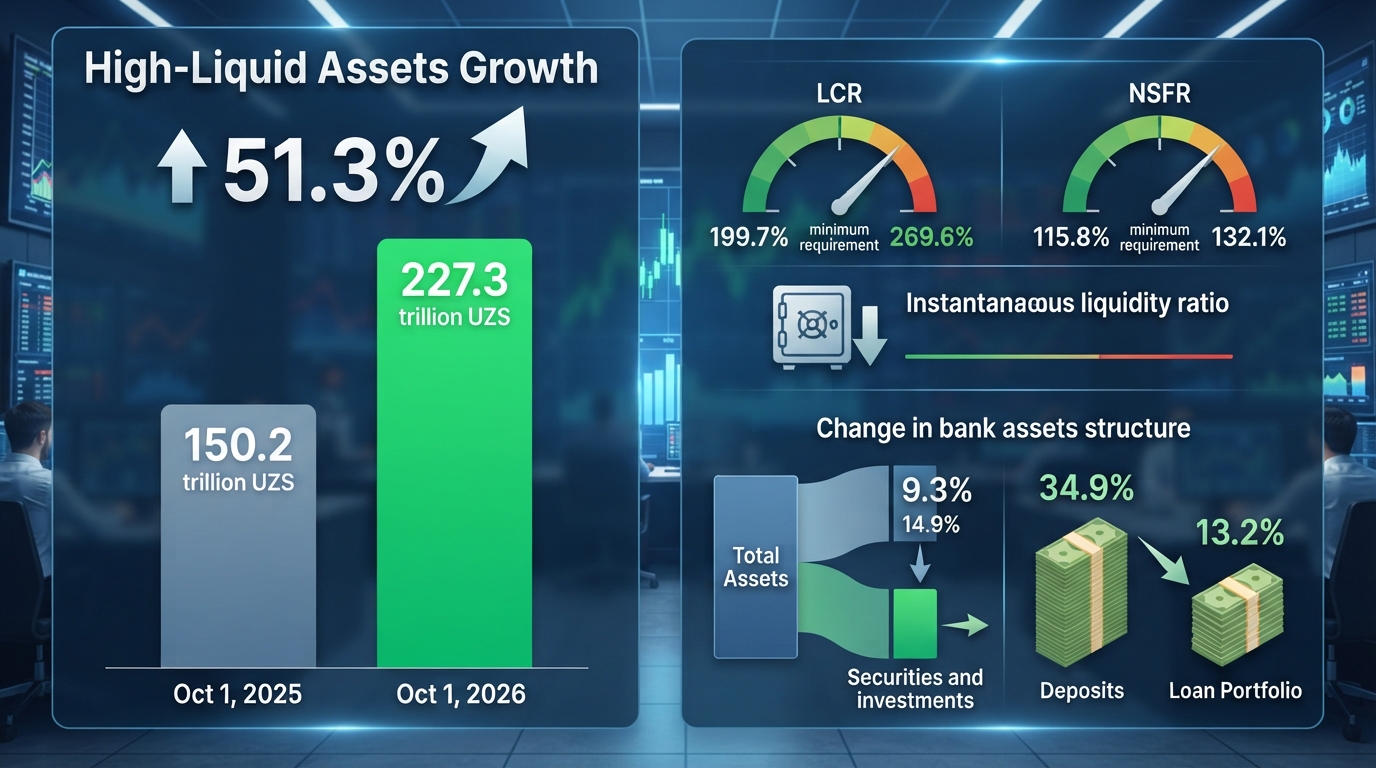
Highly liquid assets of Uzbekistan's banks increased by 51.3%
As of October 1, 2026, highly liquid assets of commercial banks of Uzbekistan reached 227.3 trillion soums, which is 51.3% more than a year earlier. As of October 1, 2025, their volume stood at 150.2 trillion soums. This was reported by the Central Bank of Uzbekistan.
In absolute terms, the growth amounted to 77.1 trillion soums, while total bank assets added 20.5% over the same period and reached 1,044.8 trillion soums.
The share of highly liquid assets in total bank assets rose from 18% to 22.4%. When calculating this indicator, the balance of highly liquid securities sold under REPO transactions is excluded from total assets.
The main liquidity ratios significantly exceed the minimum requirements. The Liquidity Coverage Ratio (LCR) reached 269.6% compared to 199.7% a year earlier, with a minimum requirement of 100%. The Net Stable Funding Ratio (NSFR) rose from 115.8% to 132.1%, with the same minimum requirement of 100%.
The instant liquidity ratio, on the contrary, decreased from 117.4% to 97.2%. However, it is almost four times higher than the minimum level of 25%.
The increase in liquidity is also reflected in the structure of bank balance sheets. Investments and securities holdings nearly doubled over the year, rising by 93.4% to 155.6 trillion soums. Their share in assets grew from 9.3% to 14.9%.
Banks' funds at the Central Bank increased by 33.7% and reached 36.2 trillion soums, while vault cash rose by 11.7% to 30 trillion soums. At the same time, funds on accounts in non-resident banks decreased by 18.8% to 44.9 trillion soums, and claims on resident banks dropped by 3.2% to 29.2 trillion soums.
The growth in liquidity occurred against the backdrop of a faster inflow of resources. Deposits grew by 34.9% over the year to 501 trillion soums, while the credit portfolio increased by 13.2% to 659.1 trillion soums. The loan-to-deposit ratio in the system decreased from 1.57 to 1.32.
In parallel, the role of borrowed funds decreased: the share of attracted loans and leasing in bank liabilities declined from 33.6% to 28.2%, while the share of deposits grew from 50.4% to 56.2%.