Debit or credit card: which one is better to use for expenses?
TBC Bank explained the difference between debit and credit cards and which one is more convenient to use in different situations. Using the example of the TBC Osmon card, the bank explained how the limit, interest-free period, and interest rates work.
**Debit or credit card: which one is better for expenses?**
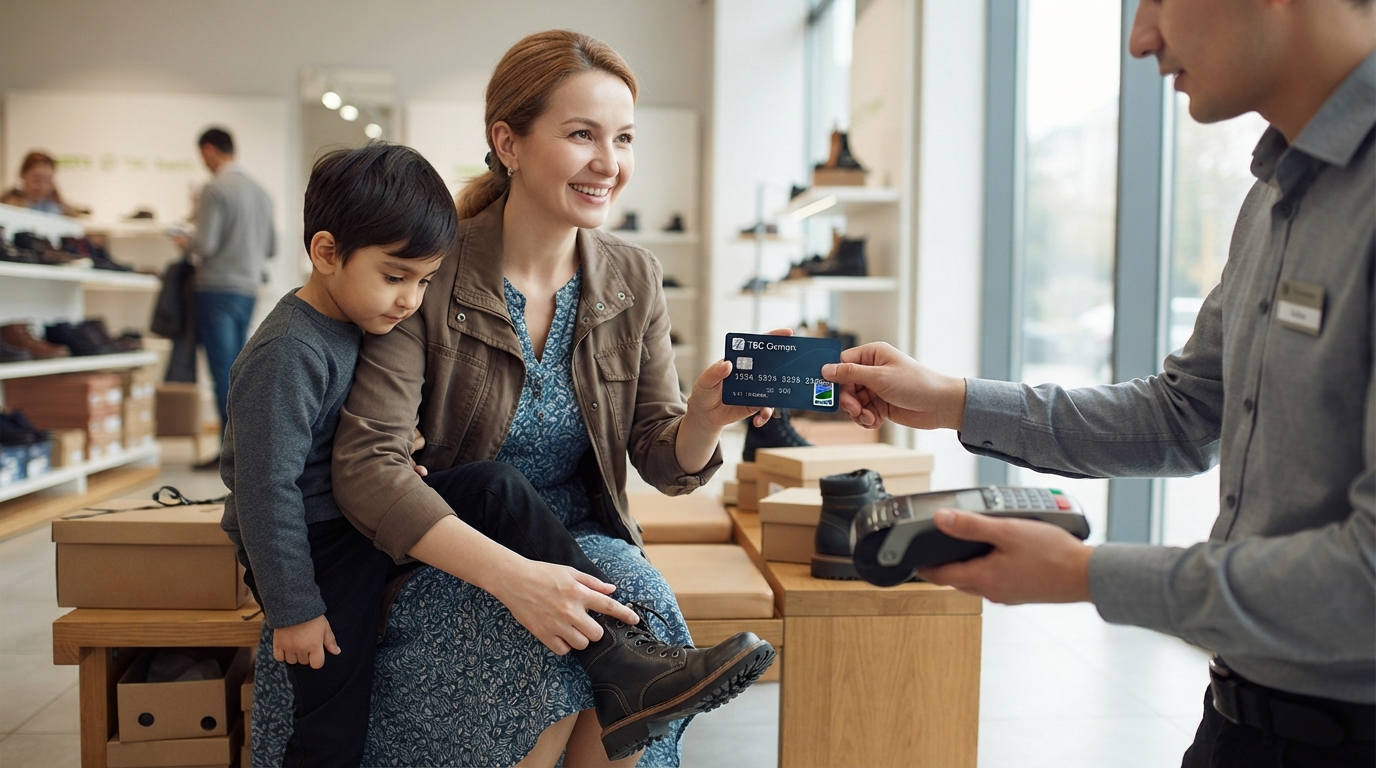
Vazira's son needed new autumn shoes, but payday was still a few days away. For this reason, she decided to pay for the purchase using a TBC Osmon credit card.
If Vazira had paid with a debit card, she would have used her own funds. A credit card works differently: the purchase is made within the limit provided by the bank, and the spent money is returned later.
A debit card is convenient for daily expenses — groceries, transport, purchases, and services. In this case, a person spends their own money on the card and has no obligation to return it to the bank.
A credit card is also designed for daily expenses, but here a person uses the bank's funds, not their own. For example, on TBC Bank's TBC Osmon card, the credit limit can be up to 50 million UZS. This is very convenient when one does not want to use their own money or when funds are needed before payday.
After purchasing the shoes, Vazira will need to return the spent amount to the bank within the specified period.
All operations on the card and the amount due can be tracked through a report. The TBC Osmon card has an interest-free period of up to 55 days. This benefit applies to purchases, but it does not apply to card-to-card transfers and cash withdrawal operations.
If a person does not repay the full amount spent on the credit card by the payment date, interest is calculated on the remaining debt. In this case, interest is charged not on the entire credit limit, but only on the spent amount. For example, if the credit limit is 10 million UZS and 1 million UZS was spent, interest is calculated specifically on that 1 million UZS debt, not on the entire limit.
If the debt is not closed on time, interest is charged on the remaining amount according to the credit card rate. For example, at a rate starting from 32% per annum, approximately 17,534 UZS of interest is calculated over 20 days for a debt of 1 million UZS.
Calculation: 1,000,000 × 32% × 20 / 365 = 17,534 UZS
The faster the debt is closed, the less interest will be paid.
The terms of the interest-free period do not apply to all operations. Different rules and commissions apply for cash withdrawals and money transfers.
Both a debit card and a credit card are suitable for daily expenses. The difference is that on a debit card, a person spends their own money, while on a credit card, the bank's money is used and returned later.
The most important thing is to familiarize yourself with the card terms in advance and not to forget the payment deadlines.
The interest rate is determined individually and ranges from 0% to 50% per annum. The maximum amount is 50 million UZS. The grace period does not apply to cash withdrawals and equivalent operations. The cash withdrawal fee is 3%, but not less than 90 thousand UZS. Failure to meet credit card obligations may lead to financial risks.