

The IAEA raises its nuclear power forecast for the sixth consecutive year. What stands between the forecast and reality?
At the 70th General Conference taking place in Vienna, the International Atomic Energy Agency (IAEA) presented a new long-term outlook for the development of nuclear power. Under the high-growth scenario, the world's installed nuclear generating capacity could increase from 377.1 GW at the end of 2025 to 1045 GW by 2050 and 1284 GW by 2060, which is approximately […]
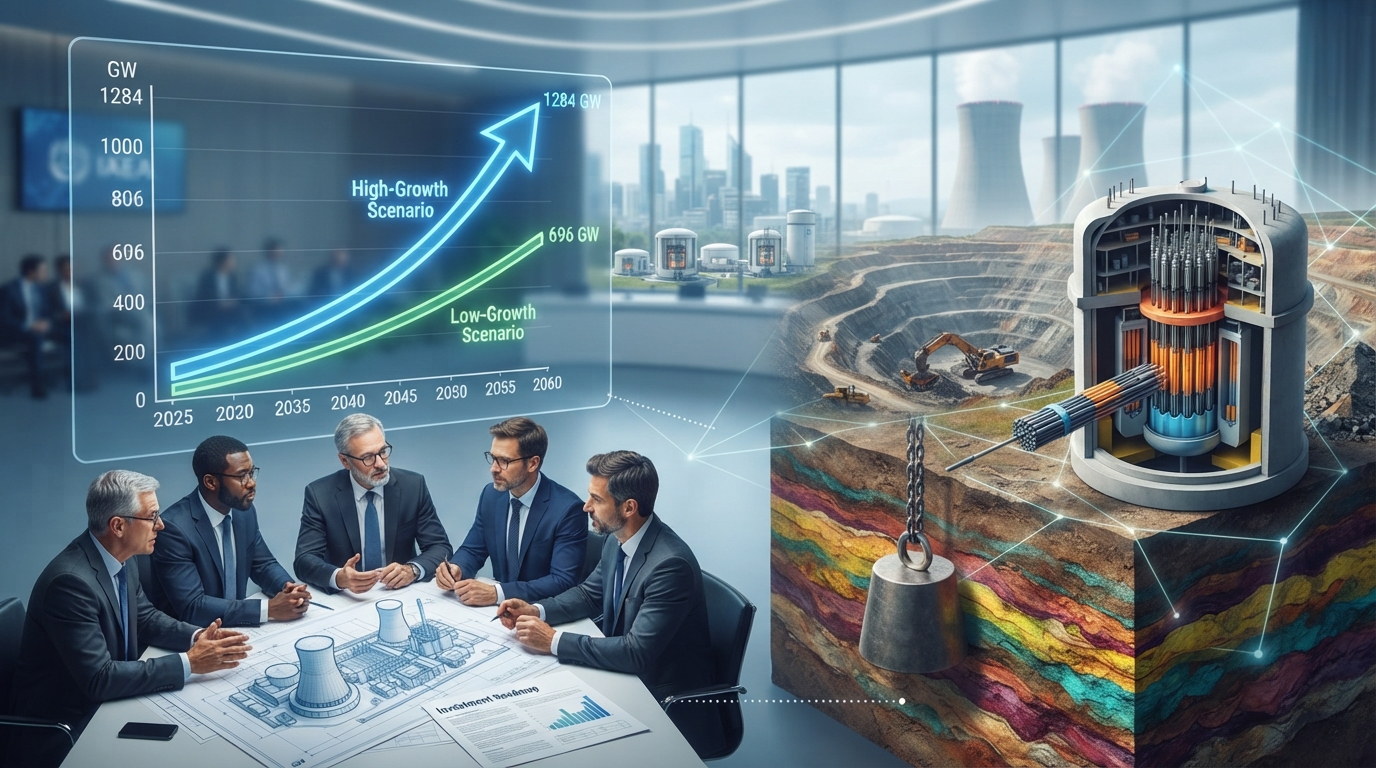
For the sixth consecutive year, the IAEA has raised its nuclear power forecast. What separates the forecast from reality?
At the 70th General Conference of the International Atomic Energy Agency (IAEA), currently taking place in Vienna, a new long-term outlook for nuclear power development was presented. In the high-growth scenario, the world's installed nuclear capacity could increase from 377.1 GW at the end of 2025 to 1,045 GW by 2050 and 1,284 GW by 2060, representing an approximately 3.4-fold increase. In the low-growth scenario, the figure would reach 696 GW by 2060.
This marks the sixth consecutive year that the IAEA has revised its estimates upward. However, the nearly twofold gap between the scenarios shows how heavily future growth depends on the conditions of its implementation. This refers to different sets of assumptions under which the industry could develop faster or slower. Hence, another question arises: what is needed for the growing interest in nuclear energy to actually translate into new capacity?
Speaking at the opening of the General Conference, IAEA Director General Rafael Grossi specifically pointed to the gap between plans to scale up nuclear capacity and the feasibility of their implementation. Among the key conditions, he named a change in financing approaches, as political will alone is insufficient to launch such capital-intensive projects.
Shortly before the conference, the agency organized a dedicated three-day seminar in Vienna for approximately 50 representatives of international financial institutions, including the World Bank, the Asian Development Bank, the EBRD, the Asian Infrastructure Investment Bank, the African Development Bank, and the OPEC Fund. Its goal was to provide financiers with a comprehensive understanding of the economics of nuclear projects, safety requirements, regulation, safeguards, and infrastructure.
The scale of the financial challenge is illustrated by an estimate from the International Energy Agency (IEA). In the APS scenario, which assumes full and timely implementation of announced energy and climate pledges by countries, annual investment in nuclear energy must rise to approximately $120 billion by as early as 2030, compared to about $65 billion today. At the same time, new nuclear power plants remain complex objects to finance. They require large upfront investments, take a long time to design and build, and delays and budget overruns increase risks for lenders and investors. For large nuclear projects, a typical return on investment period can reach 20–30 years.
Against this background, the shift in the position of international financial institutions is particularly noticeable. In June 2025, the World Bank and the IAEA signed a cooperation agreement, which the bank called the first concrete step toward returning to nuclear energy after decades of absence. The cooperation covers countries' institutional readiness, safety and regulation, extending the operation of existing NPPs, and exploring the potential of new technologies.
The growing interest in nuclear energy is already manifesting in real projects. According to the IEA, nuclear reactors with a total capacity of about 78 GW are currently under construction in 15 countries. This is one of the highest levels in the last 30 years. At the same time, the market remains highly concentrated. Over the past decade, 94% of the reactors whose construction was started globally have been of Russian or Chinese design.
There is another issue regularly discussed in the nuclear community: the age of the existing fleet. According to the IAEA, two out of every three nuclear power reactors have been operating for more than 30 years, and 45% for more than 40 years. In the high scenario, about one-third of the capacity operating in 2025 will be retired by 2060, while in the low scenario, nearly two-thirds will be decommissioned.
Part of the expectation for renewal is linked to the development of small modular reactors (SMRs). The IAEA allocates 28% of new nuclear capacity to be commissioned by 2060 to SMRs. This calculation assumes that SMRs can be brought to a much broader commercial market. For now, the scale of their practical deployment remains limited. According to the IEA, a land-based SMR is already operating in China, a floating one in Russia, and several other commercial projects are under construction in various countries, including Uzbekistan, where an integrated NPP is being built with the participation of Rosatom.
Therefore, for SMRs, the question is no longer so much about the availability of designs, but about their scaling—meaning the standardization of designs, alignment of regulatory approaches, cost reduction, and the industry's ability to transition to mass production, which only a few in the world can boast of today.
Another important document was presented in Vienna on the first day of the General Conference. The IAEA, together with the OECD Nuclear Energy Agency (NEA), released a new report, "Uranium 2026: Resources, Production and Demand," known as the "Red Book."
Identified global uranium resources recoverable at costs below $260 per kilogram exceed 8.1 million tonnes. According to the authors' estimates, this is sufficient even for the high-demand scenario up to 2050. However, the presence of resources in the ground does not yet mean their availability to the market. To achieve this, deposits must be prepared, permitting procedures completed, and new projects brought to commercial production.
Today, the operating global fleet requires about 64.5 thousand tonnes of uranium per year. By 2050, the requirement, depending on the scenario, could rise to approximately 84.8–143.9 thousand tonnes. Meanwhile, developing a new uranium mining project typically takes 15–20 years. Therefore, the authors of the report specifically emphasize the need for timely and sustained investment in exploration and the development of new projects.
For Uzbekistan, this issue is of direct significance. The country is simultaneously developing its own nuclear power industry and increasing natural uranium production. According to the State Enterprise Navoiyuran, by the end of 2025, production reached 7 thousand tonnes of natural uranium, compared to 5.2 thousand tonnes a year earlier. In April 2026, the enterprise began commercial mining at the Kizilkok deposit, which has a design capacity of up to 1.2 thousand tonnes of uranium per year.
Therefore, the new IAEA forecast is of interest to the country not only from the perspective of future global demand for nuclear generation. If capacity growth follows a higher trajectory, the need for a stable raw material and fuel base will grow along with it. For uranium-producing countries, this means the necessity to assess investments in new deposits and the long-term dynamics of the global market in advance.
The difference between the IAEA scenarios regarding the development of nuclear energy can be interpreted in various ways. It is clear that in recent years, political support for nuclear energy has strengthened, the volume of capacity under construction remains high, and international financial institutions are showing interest in the sector once again. But to expand nuclear generation, simply deciding to build new NPPs is not enough. The real scale of future growth will depend on factors such as cost, construction times, industrial supply chain capabilities, availability of personnel, replacement of aging reactors, and the timely expansion of the fuel base.
Therefore, the current IAEA forecast primarily shows a shift in expectations regarding the role of nuclear energy. How close the global nuclear fleet comes to the upper boundary of this forecast will depend on the ability of countries and the industry to turn these expectations into sustainably financed and executable projects.